Record renewables, fewer extremes: battery revenues in July
July brought record renewable generation and a return of frequent negative-price hours, yet the market remained noticeably calmer than in previous months. This piece examines why abundant renewables no longer translated into the same price extremes – and what that meant for battery revenues.
The month followed a familiar summer pattern. Renewable generation reached a new high, solar output repeatedly pushed midday prices toward zero, and negative-price hours rose again. Yet the market no longer resembled either of the extremes seen earlier: the deep oversupply-driven price collapses of spring were less pronounced and June’s scarcity-driven evening peaks had faded. For battery operators, this meant a market with fewer outliers but still meaningful spreads.
July in numbers
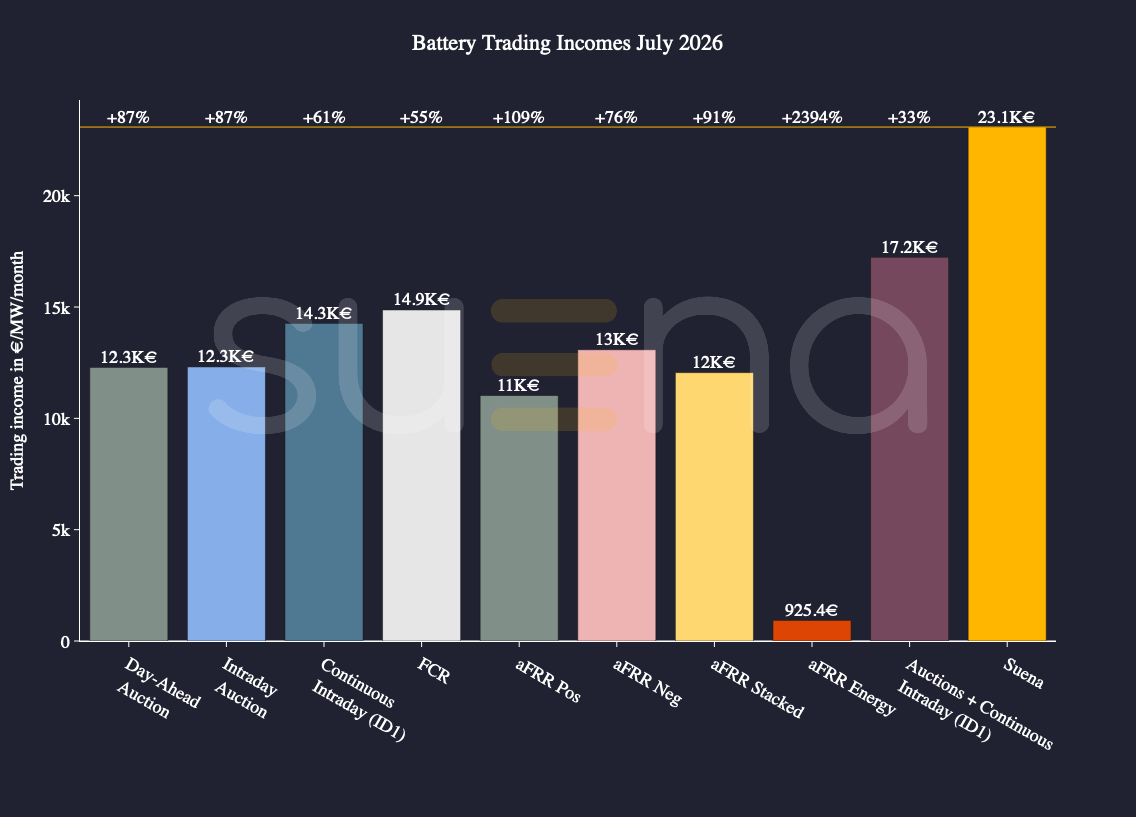
To quantify these developments, we evaluated simulated earnings for a representative 10 MW/20 MWh Grey Standalone Storage in Germany. As in previous months, individual market strategies were benchmarked against a forecast-based cross-market optimization approach.
Among wholesale markets, continuous intraday trading again delivered the strongest standalone performance, though revenues fell from €17,700 ($20,650) per MW/month in June to €14,300 per MW/month in July, a decline of about 19%. Day-ahead and intraday auctions proved considerably more stable, each reaching €12,300 per MW/month, only slightly below June levels. The combined wholesale strategy, integrating auctions and continuous intraday trading, declined from €20,300 to €17,200 per MW/month.
Ancillary service capacity revenues, by contrast, barely moved. Frequency containment reserve (FCR) remained unchanged at €14,900 per MW/month, while positive automatic frequency restoration reserve (aFRR) held at €11,000, negative aFRR at €13,000 and the stacked aFRR strategy at €12,000 per MW/month. aFRR energy revenues were the exception, falling from around €1,400 in June to just under €1,000 per MW/month.
The strongest overall performance again came from combining markets. This forecast-based cross-market optimization approach generated €23,100 per MW/month. While around 8% below June, it still exceeded the combined wholesale strategy by roughly 33%, while significantly outperforming all individual trading strategies by between 55% and nearly 2,400%.
Record renewables
July combined record renewable generation with a comparatively orderly price profile. Renewables accounted for 71.5% of German electricity generation, the highest monthly share recorded so far this year. For much of the month, renewable output matched or exceeded domestic demand around midday, repeatedly pushing residual load into negative territory.
This abundance was clearly visible in short-term price formation. The average day-ahead spot price fell to around €104/MWh, roughly €6/MWh below June, as the heat-driven scarcity of the previous month eased. At the same time, strong solar generation repeatedly pushed prices close to zero between 11 a.m. and 3 p.m. Across the second quarter, the average midday price stood at just €16/MWh, with a median of only €3/MWh. In July itself, 79 hours of negative prices were recorded, up from 52 in June.
Yet this did not translate into uniformly low prices across the day. Morning and evening hours remained materially higher, averaging around €110/MWh to €120/MWh, preserving the characteristic daily “bat-ear” price profile. The spread between the most expensive and cheapest quarter-hour reached €218.30/MWh in the second quarter, the second-highest quarterly value since 2020. Unlike the fuel-driven price spikes seen earlier in the year, this spread increasingly reflected the structural impact of high renewable penetration on intraday price formation.
For battery operators, July was therefore less about capturing a handful of exceptional price events and more about consistently monetizing recurring structural spreads across the day, while drawing on comparatively stable ancillary service revenues alongside them.
July showed the other side of the market regime seen in June. While June was characterized by heat-driven scarcity and sharp evening peaks, July returned to a more familiar PV-abundance profile, with deep midday troughs, more moderate evening ramps and softer intraday spreads.
For battery operators, the contrast is revealing. Energy-market revenues responded visibly to the change in price structure, while ancillary service capacity revenues remained remarkably stable. As a result, the cross-market stack absorbed the shift comparatively well, with overall revenues declining only moderately despite a much softer wholesale environment.
At the same time, July showed that attractive battery economics do not depend on exceptional price events. Even without June’s extreme evening peaks, recurring differences between low midday prices and higher morning and evening levels continued to create meaningful arbitrage opportunities.
This is likely to become increasingly relevant as renewable penetration grows. Battery revenues will have to perform across very different market regimes, from scarcity-driven periods to phases of pronounced solar abundance. Navigating these contrasting market regimes will increasingly depend on combining opportunities in energy markets with the relative stability offered by ancillary services.
More about
Written by
Popular Posts