Peak Energy CEO: ‘Anywhere LFP ESS goes, we go – and we do it better’

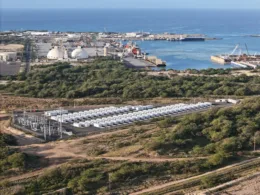
On 21 October, Peak Energy announced its oversubscribed Series B funding round which raised $108 million to advance its grid-scale passive cooling sodium-ion energy storage systems. GM Ventures led the round while other participants included LG Technology Ventures, Maverick Silicon, Infinite Capital, Eclipse and Xora Innovation. Peak didn’t disclose its valuation or the scale of GM Ventures’ contribution, but much of the Series B funding will be poured into the company’s factory in Sacramento, California, which opened in July with an annual production target of 4 GWh of Peak’s grid-scale sodium-ion battery energy storage systems (BESS).
Earlier this year, Landon Mossburg, CEO at Peak Energy, sat down with ESS News for a wide-ranging interview covering Chinese battery manufacturing domination, sodium-ion’s advantages over LFP, data center customers and deployment of grid-scale sodium-ion battery projects.
ESS News: Gigawatt-scale production of sodium-ion batteries is a big deal for a company like Peak which is only three years old. How do you plan to pull it off?
Mossburg: We’re already shipping from our pilot line in Burlingame, California, and we can do around 30 systems a year out of there. Next year, the big factory in Sacramento will get into hundreds of systems per year. We’re just getting started and it will be one of the biggest sodium-ion systems factories in the world when we turn it on. It’s highly automated but there’s still plenty of jobs for folks to do. We take a very pragmatic approach which comes from experience – we’ve all built a lot of factories before, and a lot of the company is ex-Tesla. Over-automation early on is one of the failure modes we’re trying to avoid. The pilot line where we produced our first modules was mostly by hand – the laser weld was done with a handheld laser welder but now when you walk into that factory almost all the process steps are done by robots.
Early next year we’ll probably commit to another round of large cap-ex investment. The next phase of scaling is automating material flows between stations and for that we need to bring in some of the production processes that we outsource today like stamping that are heavy cap-ex.
The fundamental cell chemistry and design work that we do is based in Denver, Colorado, and it’s a small but very capable team of about 15 or so. They work closely with suppliers and partners to inform and test and be the fastest at bringing new technology into our systems and getting it out into the world. I think that speed is a super important part of being a leader in anything that incorporates sodium-ion for the next decade, just because there’s going to be so much innovation happening so quickly.
The majority of the company, about 120 people, are in Burlingame at our pilot factory and the ESS R&D facilities. Most of our technology innovation happens at the system level, not at the cell level – ie. that’s where our passive cooling stuff is done – and that’s the special technology part of the company. We’re the only ones still to have ever done passive cooling in ESS in an application that is techno-economically viable. Now that we’ve proven what the core thesis of the company is we will continue to advance it and make our product and we’ll also announce some variants of our ESS product soon.
I think others are still trying to catch up. If you unlock passive cooling at a grid scale what else is possible? We’ve been thinking about that for probably the past two years and working on some stuff quietly in the background that we’ll announce as well coming up around the end of the year, probably. Our first system was grid-connected last year, so we’re beating that goal, but to claim you’re moving the needle in this industry, you need to be doing gigawatt-hour-scale deployments, and we will be very close to a gigawatt-hour next year. We may cross it. It might be a little tough given scaling and project timelines but certainly in 2028 we’ll cross that milestone.
What do your customers like about your technology? Why a sodium-ion battery over an LFP system?
We’re delivering in Texas as we speak, from our pilot line, and we have other projects all over the country – in California, MISO, and PJM. Anywhere LFP ESS goes, we go – and we do it better. It’s exciting to think about all the niche applications that are unserved with current technologies. Customers in places like Canada, Alaska and the Yukon, can’t install LFP because for parts of the year these places are unpopulated. So, if you leave the batteries there, they freeze, and LFP needs auxiliary power. Our ESS doesn’t need any auxiliary power and that enables these local communities to make clean energy choices and drives the cost down.
It’s the same for cities where we’re working with developers who’ve had their projects stranded because their permits have been challenged by community activists worried about fires. Those are concerns we need to listen to undoubtedly but if you’re choosing a good ESS, even if it’s LFP, your safety concerns are overblown. There are some caveats. There’s been a bit of backsliding on technology driven by the fact that China can’t access the market anymore. Generally, LFP is quite safe but we’re safer. Zinc and some flow batteries, at least on paper, have safety cases that solve these problems, but the economics are so poor that even at a large premium they struggle to make projects work.
How will you scale in a way that LFP companies and other competitors didn’t?
It’s a good position to be in to have a product that doesn’t need a massive premium to compete. We compete head-to-head on price with LFP systems and outperform them on total cost of ownership and project returns, but we also compete with them on safety and time to power and on life. The only thing we don’t compete on for regular energy projects is footprint – we’re probably about 15% less energy density at a site level. But for data center customers, they need high availability and LFP can’t provide that and the way they’re solving it is to overbuild. In the end, we’re more space efficient because you’re not having to build so much redundant capacity to serve the same load. So, on paper we are less energy efficient or energy dense at the site level but in reality we end up being better for most projects.
The market is right at the inflection point, and the world is starting to change in terms of the way that folks are thinking about sodium-ion. Lots of different companies working on new technologies are starting to make predictions that sound very similar to what we say, which is by 2035, sodium-ion will do the same thing in ESS or in EVs that LFP did in those markets.
The reason sodium-ion can win in these markets is for all the same reasons that LFP won 15 years ago: it’s cheaper, less constrained on the raw material side, longer life, better safety. Its only downside is energy density and that’s improving very quickly. It’s actually improving much faster than LFP did because it can benefit from a lot of the things we learned from bringing LFP efficiency up.
As we do that, we need to look closer at other areas that need to be addressed now and that’s where we’re going to build capability and build products and start to go to market in those areas specifically. Storage is great is but without generation you don’t have anything to store, and I think the way we do grid scale ESS today is a product of the way the technology evolved and one of the key factors that drove the architectures for grid scale storage is the fact that you have to cool it and you can already see us disrupting there as our system doesn’t have any outer enclosure, for example, but there are principles to be broken in system building and there’s more disruption possible in the way storage is built into our grid as you start to think about sodium-ion not needing active cooling etc. It allows us to do things pretty differently in a lot of ways. Everything from increased speed of deployment, reliability of the grid, and affordability of energy but it also unlocks better techno-economics for clean energy sources and for intermittent power sources that are becoming increasingly limited by dispatchability. Storage obviously solves all that.
If you look at solar plus storage, wind plus storage… that’s now relatively competitive even with cheap natural gas. But it’s not so competitive that it overcomes enough of the obstacles. You see a lot of data center customers choosing gas and it’s one of the ambitions of the company to make choosing storage so obvious that you can’t not choose it.
What do you think the long-term outlook for sodium-ion battery manufacturing is in the US?
The US has a lot of work to do. We’re in the lead position on the end application which is the most important part of the supply chain right now but we need to quickly start to bring a supply of cells and other components here domestically.
China have got about a 15-year head start on us and they put export controls on the technology now at the cathode level and they have the structural supply chain benefit that comes from the way they make steel that makes their LFP cathode precursor cheaper than the US will ever make it so I think continuing to focus on LFP is a real risk. Can it ever be viable without a subsidy?
I think that’s one of the reasons GM invested in us. They share the same view and that’s why they’re doing sodium-ion with us for ESS. We’ve got the largest proven natural reserves of soda ash which is the precursor equivalent of sodium carbonate or lithium carbonate for LFP and on the anode side we have advantages from our petrochemical industries which are the long-term target feedstock for it. The US has got to get in the game. We lost the first leg of the race and I’m encouraged by the fact we and others like Unigrid and Manna are making a lot of progress. But we need to see big industrial players invest now.
I was in Northvolt before and one of the reasons Northvolt didn’t make it was because it tried to build the entire supply chain on its own in Europe and we’re not going to repeat that mistake here. We want to do this with partners. It’s a massive market and if we attract competitors it’s good for us for many years until we have to worry about competing with each other. There’s so much demand.
China has the largest sodium-ion battery installations because they get a ton of subsidies, but we have to win entirely on merit, and it’s fun to think that a small, scrappy startup company like us can beat CATL to the largest installation again. We already beat them once in terms of getting the first product out there, but we’ll do it again next year with the biggest installation.
China have got about a 15-year head start on us and they put export controls on the technology now at the cathode level and they have the structural supply chain benefit that comes from the way they make steel that makes their LFP cathode precursor cheaper than the US will ever make it so I think continuing to focus on LFP is a real risk. Can it ever be viable without a subsidy? One of our first investors was TDK Corp, which is a Japanese conglomerate but they’re the parent company of ATL which is the company that CATL spun out of.
Written by
Comments
Popular Posts