Four-hour BESS undercuts gas peakers in 43 global markets
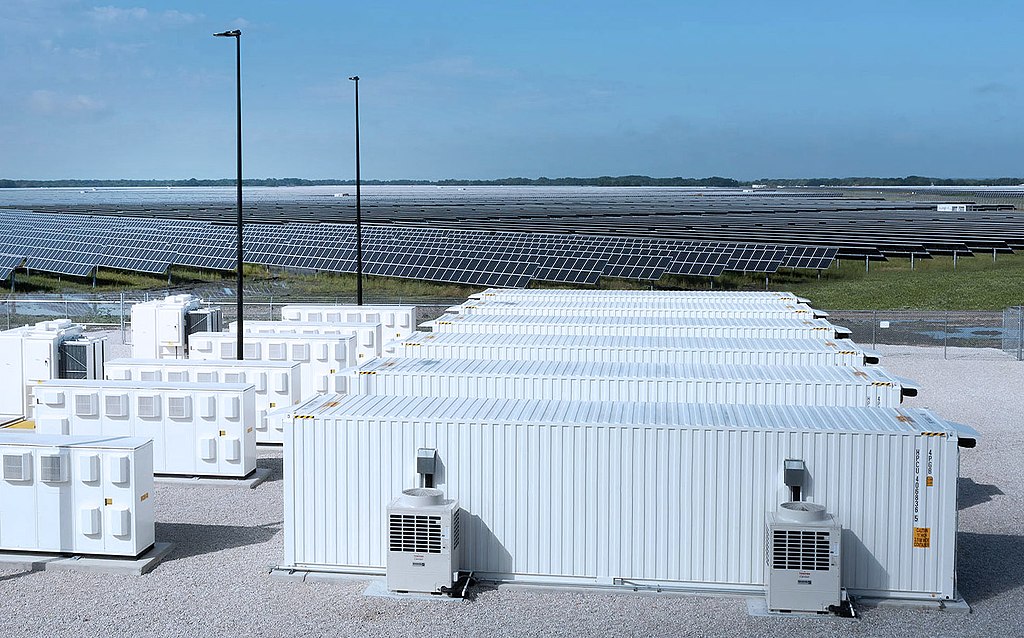
The levelized cost of electricity (LCOE) for four-hour battery storage has crossed a critical threshold, falling below open-cycle gas turbines across all 43 global markets modeled by Wood Mackenzie. However, while expanding manufacturing and volatile fuel prices drive gas peaking out of the market globally, North America faces a distinct trajectory marked by near-term trade barriers, policy shifts, and surging power demand from data centers.
Advancing technologies and manufacturing scale are redrawing global power market dynamics. Wood Mackenzie’s latest Levelized Cost of Electricity (LCOE) report shows that single-axis tracker solar is now the lowest-cost new-build power source in 43 of 48 modeled markets, with four-hour battery storage decisively beating open-cycle gas turbines on cost.
“This economic shift is decisive and widening,” said Ahmed Jameel Abdullah, principal analyst at Wood Mackenzie. “Gas turbine shortages and rising fuel volatility are driving up peaking costs, while expanding battery manufacturing continues to push storage costs down.”
Yet, North America stands out as a key exception in long-term cost trajectories, heavily influenced by domestic trade policies, supply chain protections, and load pressures.
Tax incentives
Unlike international markets benefiting from low-cost Chinese equipment exports, North American clean energy developers face immediate cost headwinds. Near-term solar costs across the United States and Canada remain elevated under a wave of tariffs, anti-dumping and countervailing duty (AD/CVD) actions, and Section 232 import restrictions.
Utility-scale solar developers maintain a buffer thanks to 168 GW of safe-harbored capacity, but module prices are still projected to climb ~5% annually through 2030. Distributed generation bears the brunt of the pressure, with residential and commercial solar module prices forecast to jump 6% in 2027 and an additional 14% in 2028.
For energy storage, Federal tax credits under the Inflation Reduction Act (IRA) continue to provide a critical competitive advantage, helping offset strict Foreign Entity of Concern (FEOC) sourcing restrictions and domestic supply bottlenecks. While a temporary cost increase is anticipated when the Investment Tax Credit (ITC) phases out in the late 2030s, hardware commoditization, alternative cell chemistries, and localized manufacturing expansion are expected to drive long-term storage LCOE down 10% by 2060.
Simultaneously, massive load growth from AI and data center development is forcing utilities to re-evaluate capacity planning. Thermal capital costs remain elevated due to a supply deficit cycle in gas generation equipment through the late 2030s, strengthening the long-term economic case for paired renewables and storage despite near-term headwinds.
Overseas markets
Outside North America, global storage and solar costs are declining at a faster rate due to unhindered supply chain integration:
- Middle East & Africa: Utility-scale single-axis solar leads globally at $37/MWh, on track to drop below $20/MWh in Saudi Arabia and the UAE by 2033. Four-hour battery storage sits at $120/MWh in 2026 and is forecast to fall 33% to $80/MWh by 2035, displacing open-cycle gas peaking across every gas market in the region.
- Asia Pacific: China remains the global cost anchor with a grid-scale storage benchmark LCOE more than 55% below the rest of the APAC average ($134/MWh). Competitive Chinese exports are expected to drag the regional average down to $92/MWh by 2036, though tariff-heavy markets like Japan and Australia will maintain a premium.
- Europe: High levelized carbon costs—projected to pass fuel costs by 2030 – make Europe the most expensive region for fossil-fuel generation. Turnkey battery storage capex saw a minor 2% uptick in 2026 following a 10% cell price rebound, but costs are projected to fall 12% by 2031.
- Latin America: Driven by top-tier solar irradiation, single-axis tracker solar leads all generation sources. Grid-scale battery storage LCOE is forecast to plunge 42% by 2060, supported by regional storage mandates and grid stability procurement.
Looking ahead
The convergence of falling storage costs and high gas turbine prices is shifting how grid operators plan baseline and peaking capacity. While North American developers must navigate trade restrictions and high load demand, the underlying economics continue to favor renewable-plus-storage builds over new thermal peaking plants.
“The structural shift we are tracking is no longer just about renewables becoming competitive,” Abdullah said. “It is about storage and solar together redefining what the economics of a power system look like. The combination of falling storage costs and world-class renewable resources is closing off the economic case for new gas peaking capacity globally.”
From pv magazine USA
More about
Written by
Comments
Popular Posts