Sodium-ion: Time to prove its worth
Until late April 2026, the prospects of sodium-ion battery technology achieving large-scale industrialization were taken with a grain of salt.
That perception shifted when industry heavyweights CATL and HyperStrong signed the largest sodium-ion battery supply agreement to date. The 60 GWh deal spans three years and will involve close collaboration between the strategic partners on technology R&D, product applications, and project deployment.
“From our perspective, this cooperation is not only about securing future supply capacity, but also about accelerating the industrialization and commercialization of sodium-ion storage technology,” Jianhui Zhang, founder, chairman and CEO of HyperStrong, told ESS News.
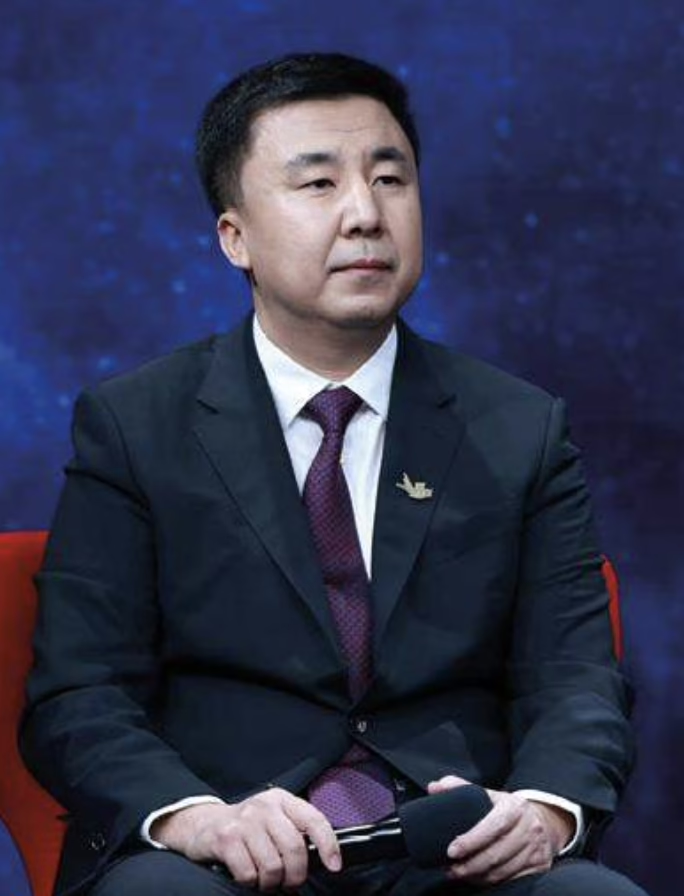
He described sodium-ion batteries as an important complementary pathway rather than a replacement for lithium-based systems. In a more diversified technology landscape, different chemistries would serve distinct applications based on their strengths, he added, noting that sodium-ion is expected to be used in utility-scale storage, high-cycle applications, data centers, and emerging “AI + energy” infrastructure use cases.
HyperStrong plans to initially advance demonstration projects and early-stage commercial deployments of sodium-ion batteries in the Chinese market, before gradually expanding into global markets based on operational data and engineering experience gained from these projects.
“At present, both domestic and international markets are showing strong interest in the potential of sodium-ion technology, particularly its suitability for long-duration storage in the four to six hour range and beyond, its wide-temperature operating capability, high safety performance, and long-term lifecycle value of 15 years or longer,” Zhang said.
The technological shift does not come out of the blue. As early as 2021, CATL released its first sodium-ion battery with an energy density of 160 Wh/kg and a promised 200 Wh/kg in the future. In late 2023, the world’s largest battery cell maker said that it had already established a basic industrial chain for sodium-ion batteries and achieved mass production capabilities.
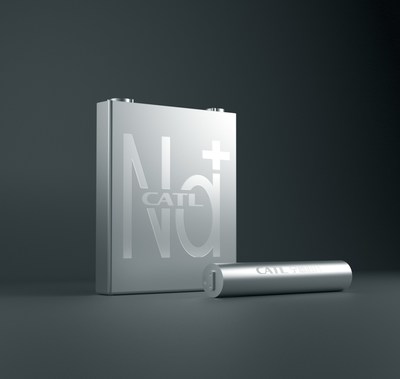
Fast forward to 2026 and after several milestones in the development of sodium-ion for EV applications, CATL unveiled what it describes as the world’s first sodium-ion platform designed specifically for energy storage, announcing commercial deployment within the same year. Its latest product is a 300+ Ah large-format cell with energy density of about 160 Wh/kg, system energy conversion efficiency of 97%, cycle life of more than 15,000 cycles at 80% capacity retention, and an operating temperature range of -40 C to 70 C.
Meanwhile, HyperStrong, as China’s leading energy storage system integrator and one of the five largest globally, has been building technical capabilities in sodium-ion storage since 2021. Its work spans cell characterization, voltage platform adaptation, battery management system (BMS) control strategies, thermal management, and lifecycle operation modeling – foundational efforts that underpin the 60 GWh deal.
Chemistry context
But while the deal is widely viewed as a milestone, its importance should not be overstated. Lithium iron phosphate (LFP) will continue to rule the roost in the battery energy storage space for the foreseeable future, although cost competitiveness may tip in favor of sodium-ion sooner rather than later.
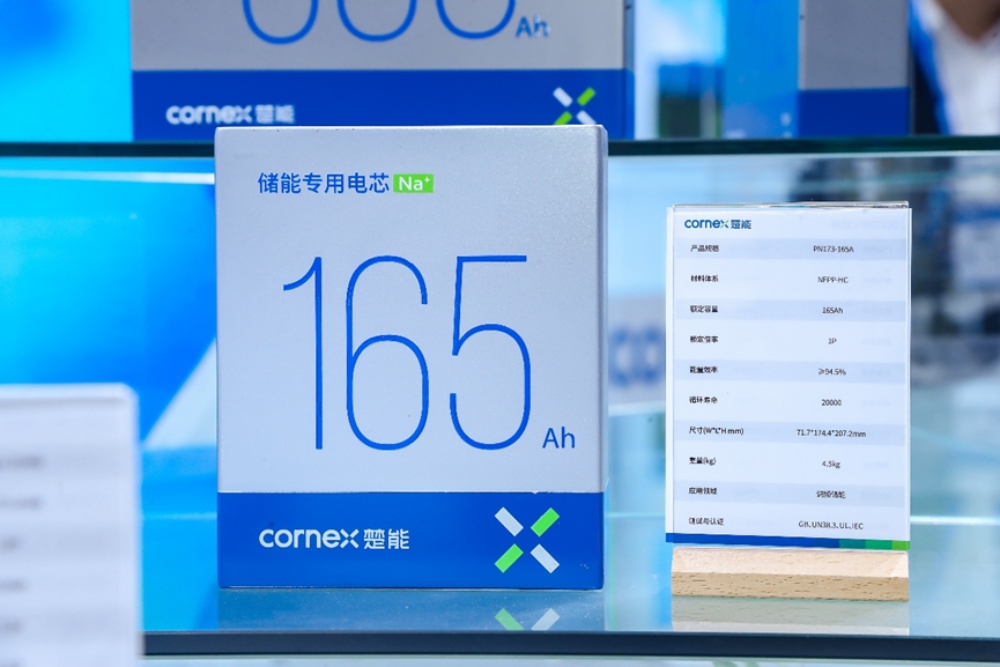
Analysts at London-based CRU Group expect sodium iron pyrophosphate (NFPP) – the sodium analogue of LFP – to reach cost parity with LFP in 2028 and potentially surpass it later this decade.
While often treated as a single chemistry, sodium-ion – similarly to lithium-ion – includes distinct cathode chemistries. Prussian blue/white, layered oxides, and polyanions (NFPP) are at different stages of maturity and not directly comparable. CRU takes NFPP as the foundation for its modeling based on analysis of major industry players and their preferred chemistry.
“Despite NFPP’s lower energy density than its Prussian Blue analogue and layered oxide counterparts, the chemistry boasts a much longer cycle life due to its more robust crystal structure, which is critical for BESS applications in particular, especially as 20-year-plus warranties become commonplace in the industry,” said Ed Rackley, head of energy storage analysis and forecasts at CRU.
Scale test
Ultimately, new battery chemistries are proven on the factory floor, and these remain first-generation products. McKinsey & Company’s Battery 2035 report sets a benchmark for battery manufacturers to reach yields above 95% and overall equipment effectiveness of at least 85% within 18 months of producing their first cells. In May 2026, CATL was not ready to tell ESS News whether this target is achievable for its sodium-ion cells, or to disclose expected initial and future scrap rates. Still, it is fair to assume that if any manufacturer in the world can achieve such performance at scale, it is likely CATL.
“The business of battery technologies, whether it is sodium-ion or lithium-ion, is a cost-optimization and yield improvement game,” said Arthur Claire, director of technology at Sinovoltaics, a quality assurance consultant for battery storage and solar developers. “Now, lithium-ion manufacturing plants have been around for some years, and they have a massive headstart in terms of experience and yield improvement compared to sodium-ion.” As a result, a steep learning curve for sodium-ion is to be expected.
Sinovoltaics has already conducted factory audits in the sodium-ion space and identified some specific challenges. “We see the coating phase of the manufacturing process as a critical step to master,” Claire said.
Depending on cathode chemistry, manufacturers must optimize slurry formulation, drying profiles, and electrode architecture differently. In this regard, layered oxide sodium-ion cathodes are considered the most advanced pathway for rapid and lower-risk scale-up compared with Prussian white/blue or polyanion systems. They are also viewed as the most lithium-ion-compatible option, as they align most closely with existing lithium battery manufacturing processes.
CATL used Prussian white/blue in its first-generation sodium-ion products in 2021. Five years later, its latest product is based on a layered oxide composite cathode. Since 2016, CATL has invested nearly CNY 10 billion ($1.5 billion) in sodium-ion R&D. The company said it has significantly improved energy density through morphology control and surface modification.
On the manufacturing side, it claims to have addressed key scale-up challenges in hard carbon anode production – such as foaming and moisture control – using approaches including angstrom-level pore-size tuning, surface molecular water-locking, and adaptive dynamic formation, all aimed at ensuring batch-to-batch consistency at scale.
However, from a product quality perspective, the introduction of new battery cell technologies is not plain sailing. While CATL’s latest sodium-ion platform is said to be compatible with its existing 587 Ah lithium-ion cell, the system integration process will require additional engineering during the early stages of commercialization.
“Because sodium-ion batteries differ from LFP in their electrochemical characteristics, voltage platform, and charge-discharge behavior, system-level adaptation and optimization are still required,” HyperStrong’s Zhang explained.
HyperStrong aims to integrate sodium-ion technology into its existing storage platform architecture through targeted system-level upgrades, rather than building an entirely separate platform from scratch. This includes optimizing battery management system strategies, thermal management logic, operating parameter settings, and lifecycle operation models.
“We see this effort as a necessary step in building long-term system integration capabilities and operational experience under complex real-world conditions,” Zhang said.
Next phase
If CATL delivers on the supply agreement, sodium-ion manufacturing will enter a new phase and establish itself as a proven scalable technology. That said, the scale-up challenge is likely to unfold very differently for newcomers. The learning curve will be steeper for the growing number of sodium-ion startups.
“While lithium-ion manufacturing giants like CATL can draw on years of operational experience from lithium-ion production, the same cannot be said for new entrants that began manufacturing sodium-ion batteries from day one,” said Claire of Sinovoltaics.
Indeed, according to the Benchmark Mineral Intelligence (BMI) Gigafactory Database, around two-thirds of projected sodium-ion pipeline capacity by 2035 is tied to tier-3 producers. Just 10% comes from tier-1 manufacturers – companies that have already demonstrated the ability to produce battery cells at scale for customers outside China. The picture is markedly different for lithium-ion batteries, where more than 40% of capacity is associated with tier-1 producers, compared with around 20% from tier-3 players.
“Growth in the sodium-ion market is dominating the narrative right now, and we’re tracking 660 GWh of pipeline capacity by the end of the decade,” said Evan Hartley, research manager at BMI. “Most of this capacity – 433 GWh – is coming from tier-3 market entrants. Tier-1 producers like CATL are expanding rapidly, however, and have the resources to scale output very quickly in response to demand.”
CATL is not the only cell manufacturer venturing into sodium-ion. BYD, EVE Energy, Gotion High-Tech, Envision Energy, Great Power and HiNa Battery are among the established Chinese companies with sodium-ion products.
According to the BMI database, China currently accounts for 99.6% of global sodium-ion manufacturing capacity, a figure projected to decline only slightly to 98% by 2030. By the end of the decade, the United States is expected to be marginally ahead of Europe as startups continue entering the sector on both sides of the Atlantic.
Still, some of the industry’s most ambitious battery manufacturing hopefuls – including Europe’s Northvolt, pursuing both lithium and sodium-ion technologies – have already struggled or collapsed under the weight of scaling challenges inherent to battery cell manufacturing. In the United States, companies such as Natron Energy, a Stanford University spinout that unveiled ambitious plans for a 24 GW sodium-ion gigafactory in the US, has also ceased operations.
Battery cell manufacturing remains far from straightforward, and ultimately it is product quality, manufacturing yields, and long-term reliability that will determine which players survive the scale-up.
“If I were buying sodium-ion cells today, I would look for suppliers with proven manufacturing experience and strong insurance coverage in the event of bankruptcy,” Claire of Sinovoltaics said. “From a technical perspective, I would also require validated – not simulated – degradation curves across different C-rates, depths of discharge (DoD), and operating temperatures.”
Pros and cons
Sodium is thousands of times more common than lithium, making it widely available, potentially lower cost, and less exposed to supply constraints. It is safer, has a longer cycle life, and is able to tolerate harsher operating conditions.
Compared to lithium alternatives, sodium-ion performs particularly well in certain applications: extreme temperature environments (especially cold weather), high C-rates, and AI data centers.
It has lower volumetric and gravimetric energy density, meaning larger and heavier systems for the same amount of energy, but since it has much lower thermal runaway risk than lithium-ion chemistries, it only requires simple passive cooling.
This feature article by Marija Maisch appeared in the July edition of the first ESS News print magazine, distributed widely at The smarter E Europe 2026. It can be read in digital form here.
More about
Written by
Popular Posts