India may commission 45-50 GWh of BESS in fiscal 2027, 2028
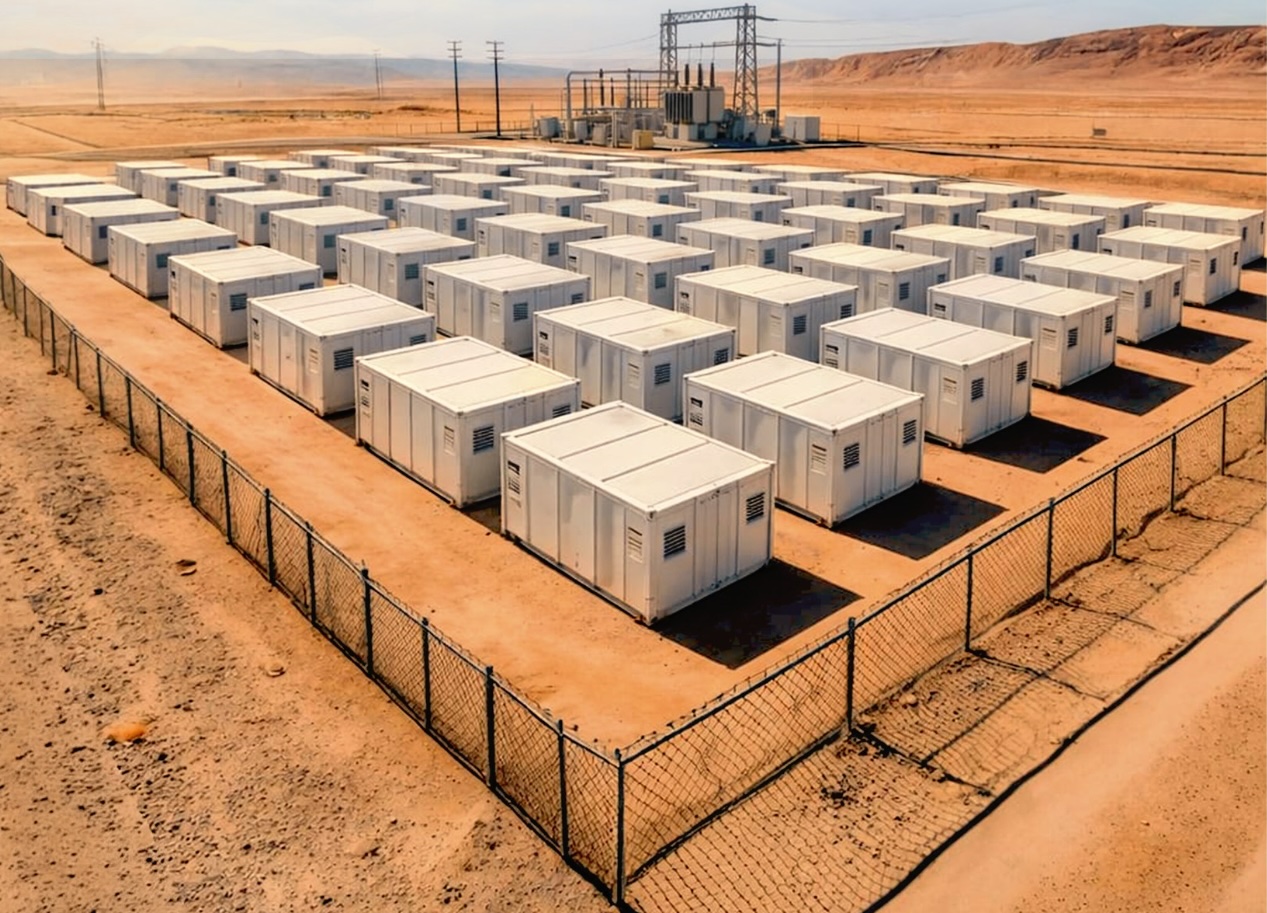
India is likely to commission 45 GWh to 50 GWh of battery energy storage system (BESS) capacity in fiscal years 2027 and 2028, compared with just about 1 GWh commissioned as of the end of fiscal 2026, according to Crisil Ratings. The expansion is supported by a strong project pipeline and continued policy support.
About 50 GWh to 55 GWh of BESS capacity is currently scheduled for commissioning during the two fiscal years. However, about 8 GWh to 9 GWh of the awarded capacity faces a higher risk of delay, mainly because of weak project returns and limited implementation experience among some developers, Crisil said.
The analysis covers bids awarded between fiscal 2024 and fiscal 2026 across nearly 100 renewable energy developers.
The government has accelerated storage-linked auctions to support the integration of a larger share of renewable energy into the national power grid. Projects incorporating BESS accounted for nearly 40% of total auctioned capacity in fiscal 2026, up sharply from about 5% in fiscal 2024 and fiscal 2025.
Of the 50 GWh to 55 GWh of BESS capacity scheduled for commissioning across fiscal 2027 and fiscal 2028, about 40 GWh has been awarded through government-led auctions, where distribution utilities are the offtakers. The remaining 10 GWh to 15 GWh is expected to serve commercial and industrial consumers directly or be deployed in the merchant market.
“Nearly 21% of the under-construction BESS capacity, equivalent to about 12 GWh, faces weak return potential which may lead to some delays in commissioning. The risk has emerged because battery prices have hardened in 2026, while tariffs bid out for these projects were relatively low,” said Manish Gupta, senior director and deputy chief ratings officer at Crisil Ratings. “Developers typically procure batteries about a year after securing project bids. Consequently, most projects awarded in 2025 are now exposed to higher battery prices, which have rebounded from the lows witnessed in 2025. As the battery prices were consistently coming down till 2025, developers appeared to have bid aggressively on the assumption that prices would continue their downward trajectory.”
Battery prices have increased, and at prevailing levels, project returns may be insufficient to achieve the typical target internal rate of return (IRR) of 12% to 14%, Crisil said. Consequently, developers may defer implementation in anticipation of more favorable battery pricing. Crisil estimates that a project with a tariff of INR 220,000 to INR 250,000 per MW per month and battery prices of $55/kWh to $65/kWh would generate an IRR of 12% to 14%.
“Approximately 8-9 GWh out of this 12 GWh of the planned capacity is exposed to an additional challenge: limited implementation experience among project sponsors,” said Ankit Hakhu, a director at Crisil Ratings. “While BESS projects typically face relatively lower land acquisition and connectivity-related challenges compared to conventional renewable energy projects, equipment procurement remains a key risk given the sector’s continued dependence on overseas suppliers for batteries and other critical components. Developers with limited scale or procurement track records may face challenges in securing equipment on competitive terms, which could adversely impact IRRs. Consequently, any increase in procurement costs, coupled with execution-related challenges, could moderate IRRs and/or result in delays in project commissioning. Early signs of these pressures are already evident across parts of the under-construction pipeline with projects getting stranded.”
That said, most awarded capacity remains either in the development stage or in the early phases of construction. The sector continues to depend heavily on overseas suppliers for batteries and other critical components. While long-term battery demand is underpinned by strong structural drivers, the potential impact of geopolitical developments and disruptions to global supply chains warrants close monitoring, according to Crisil.
The growing need for energy storage stems from the rising share of solar and wind, which accounted for 39% of India’s installed power generation capacity and about 15% of electricity generation in fiscal 2026. As of the end of fiscal 2026, India’s total installed power capacity stood at 533 GW, of which renewable energy accounted for about 206 GW.
However, renewable generation is intermittent by nature, which has increased the need for firm and peak-hour power supply and thus for energy storage, particularly BESS. The requirement is especially acute for solar because electricity demand typically peaks in the evening, when solar generation is negligible. BESS can address this mismatch by storing surplus solar power during periods of high generation and supplying it during periods of elevated demand.
From pv magazine India
More about
Written by
Popular Posts